
Highlights
| Issue Size – 43,34,09,090 shares | Issue Open/Close – 17 Aug / 19 Aug, 2026 |
| Price Band (Rs.) 57 – 60 | Issue Size (Rs.) – 26,000 mn |
| Face Value (Rs) 10 | Lot Size (shares) – 250 |
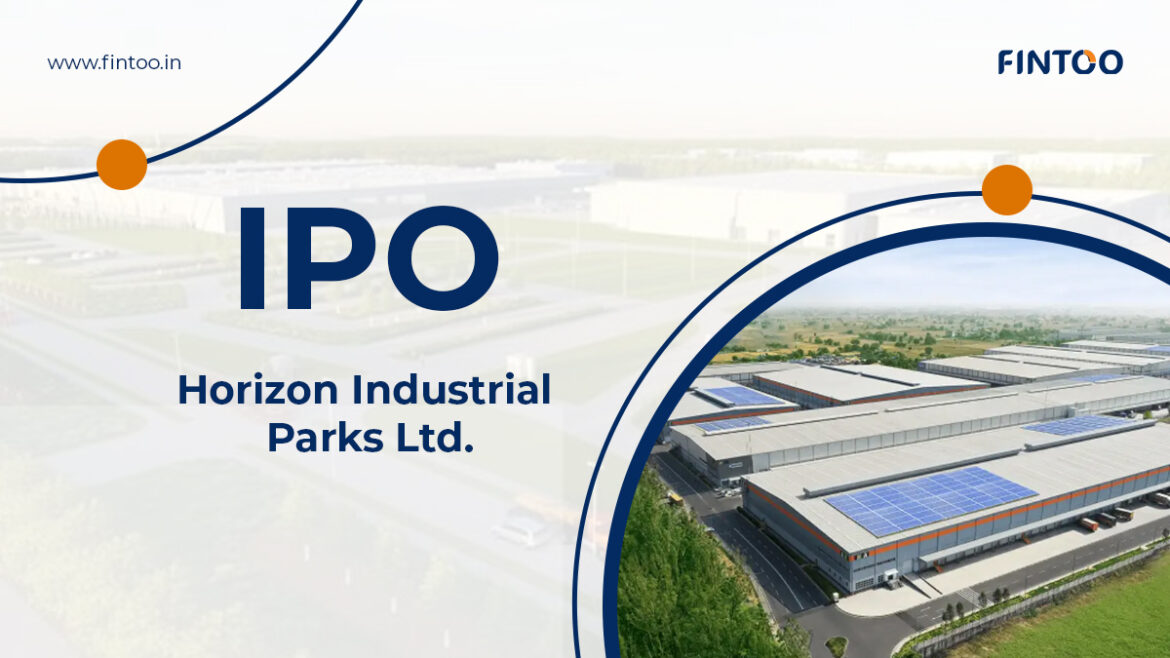
Horizon Industrial Parks Limited (HIPL) incorporated in 2009, is an India’s largest industrial and logistics infrastructure developer, owner and operator which offers Grade A quality fulfilment centers (warehouses), industrial facilities, and in-city centers across the country’s major industrial and consumption hubs.
Their solutions include, among others, built-to-suit facilities, fully fitted plug-and-play facilities, cold storage, energy solutions, on-site staff accommodation, racking and material handling equipment (MHEs), all designed to support efficient operations.
HIPL’s PAN India network consists of 45 assets spread across 10 cities including Delhi-NCR, Mumbai, Bangalore, Chennai, Pune, Hyderabad, Ahmedabad and Nagpur, totalling 58.58 million square feet (msf) out of which Operational Network spans across 28.55 msf, with a committed occupancy rate of 93.56 pct.
HIPL served a marquee customer base of over 118 customers, across key sectors of the Indian economy, including e-commerce, retail, FMCG, renewable energy, auto-ancillary and manufacturing. HPIL scale, technical capabilities, network of strategically located sites and full-service offerings allow them to partner with both MNCs and domestic companies seeking to establish storage or manufacturing facilities in India.
Out of the total proceeds of Rs. 26,000 mn, Rs. 22,500 mn would go towards repayment/pre-payment, in full or part of certain borrowings availed by the company and its subsidiaries. ~Rs. 3,500 mn would go general corporate purposes.
Key Highlights
- India’s Grade A and Grade B warehousing and industrial stock stood at 548.9 msf, which remains less than half of Chicago’s 1.3 bnsft as of FY26, underscoring the substantial growth potential ahead. The current stock expected to grow 18.4 pct CAGR over CY25-30, potentially crossing 1.2 bnsft by CY30.
- Development Network is well-placed to capture this growth, with 30.03 msf of within-the fence development, including 7.22 msf of Near-Term Deliveries and 22.81 msf of planned projects expected to be delivered over the next four to five years. As of FY26, HIPL have pre-contracted 2.57 msf to customers across eight locations.
- HIPL diversified their revenue sources with no single customer contributing more than 10 pct of their gross rentals in their operational network as of FY26. Their top 10 customers basis gross rental accounted for only 41.43 pct of total gross rentals and contributed 41.65 pct of committed Operational Network.
- HIPL possess engineering and technical capabilities that enable them to execute complex industrial projects while maintaining cost discipline. Their assets are built to Grade A+ specifications, incorporating advanced design standards such as FM2-compliant flooring, high floor load capacities, wide column spans and modern fire protection systems. By partnering with HIPL, customers can reduce their upfront capital expenditure and accelerate their time-to-market.
- HPIL target acquiring large, contiguous land parcels typically ranging from 50 to 100 acres in strategically selected locations within one- or two-hours driving distance from major city centers. These locations are suitable for both fulfilment centers and industrial facilities. Acquiring large land parcels enables scalability, supports campus style development with integrated amenities and unlocks economies of scale by optimizing overall infrastructure cost.
- HPIL’s key growth strategies include (i) To drive organic growth through build-out and stabilization of existing assets (ii) expand in-city logistics network – a powerhouse of growth (iii) continue acquisitions supported by strong cashflows and sustainable debt (iv) expand value-added service offerings to more customers (v) do strategic expansion into new segments.
- The sales of the company have grown by 73.80 pct CAGR over FY24-26 and EBITDA has grown 100.30 pct CAGR, while losses continue to increase significantly from 2024. In FY26 the company reported sales of Rs. 6,914 mn, rose 77.15 pct YoY. EBITDA of the company increased 79.24 pct YoY to Rs. 6,078 mn. In FY26 the company posted loss of (2,037) mn, widened as compared to FY25 loss of Rs 2,037 mn.
Key Risk
- Historically, the company has faced cost overruns in their business. Any future overruns may affect companies’ business.
- HIPL is exposed to the risks pertaining to land scarcity and the limited supply of land, increasing competition and applicable regulations, which may adversely affect their business and results of operations.
Financial Performance
| Particulars (Rs. mn) | FY24 | FY25 | FY26 | CAGR | YoY |
| Sales | 2,289 | 3,903 | 6,914 | 73.80% | 77.15% |
| EBITDA | 1,515 | 3,391 | 6,078 | 100.30% | 79.24% |
| EBITDA Margin % | 66.20% | 86.89% | 87.91% | ||
| Profit/Loss | (1,622) | (1,788) | (2,037) | N/A | 13.93% |
| Profit/Loss Margin % | (70.86)% | (45.81)% | (29.46)% | ||
| RoNW % | (59.46) % | (136.35) % | (4.23) % | ||
| Debt to Equity | 5.72 | 6.96 | 1.22 |
Source: – RHP.
Valuation
Horizon Industrial Parks Limited (HIPL) offer clients Grade A quality fulfillment centers (warehouses), industrial facilities, and in-city centers across the country’s major industrial and consumption hubs. Their comprehensive business ecosystem provides a holistic end-to-end solution that enables customers to operate seamlessly and reduce time-to-market. At the upper end of the price band of Rs. 60, the issue is priced at an EV/EBITDA of 28x its FY26 post issue capital. The issue appears to be fully priced.
Disclaimer: The views shared in blogs are based on personal opinions and do not reflect the company’s views. Investment involves risk, and it is advisable to consult a financial advisor before making any investment through the app. The decision to invest is solely that of the investor, and the company or its communication cannot be held responsible for it.