
Highlights
| Issue Size – 11,90,47,619 shares | Issue Open/Close – 16 Sep / 18 Sep, 2026 |
| Price Band (Rs.) 79 – 84 | Issue Size (Rs.) – 10,000 mn |
| Face Value (Rs) 10 | Lot Size (shares) – 178 |
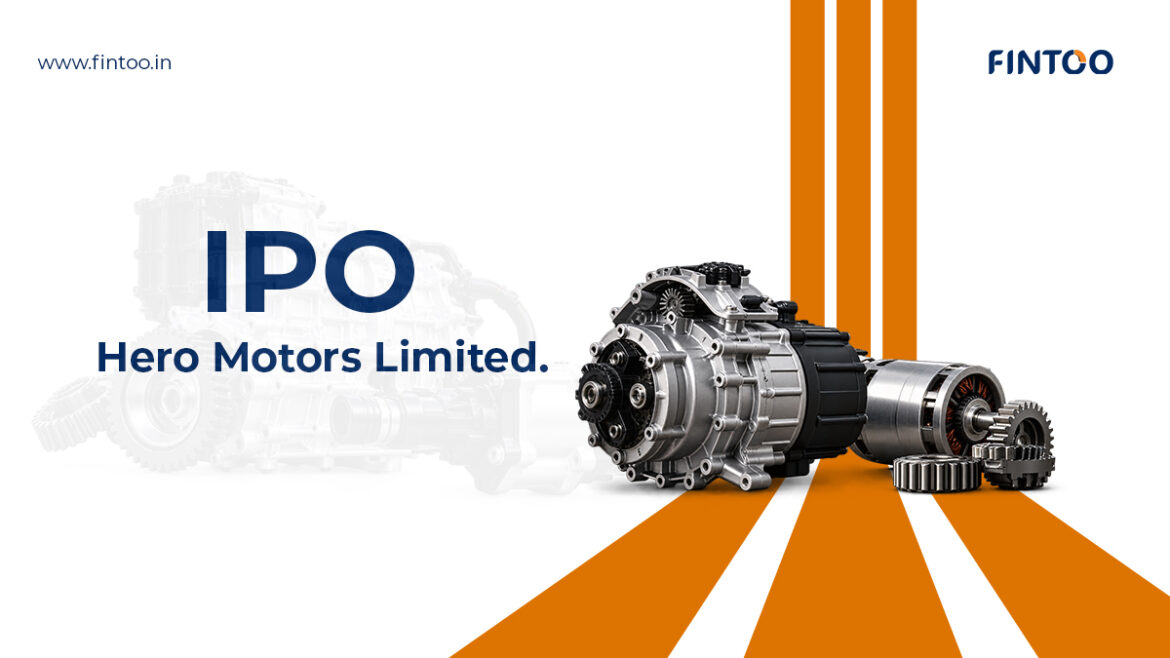
Hero Motors Limited (HML), incorporated in 1998, is an automotive technology company engaged in designing, developing, manufacturing and supplying engineered powertrain solutions to automotive original equipment manufacturers (OEMs) across the US, Europe, India and ASEAN region. They provide integrated solutions for both EV and Non-EV powertrains, serving 2Ws, performance automotive, e-bikes, off-road vehicles, EV and hybrid cars, heavy-duty vehicles and eVTOL applications.
HML offers system-level and component-level solutions covering designing, prototyping, validation, development and delivery of powertrain systems. It is recognized for its expertise in continuously variable transmissions (CVT), EV transmissions, electric motors, integrated drive units and gear sets.
HML’s operations are divided into Powertrain Solutions and Alloys & Metallics (A&M) segments. Powertrain Solutions comprises Gears and Transmissions (G&T), serving automotive and mobility applications, and Bike Powertrain (BPT), focused on micro-mobility applications and global e-bike manufacturers. The A&M segment provides sheet metal and tubular assemblies and components primarily to automotive OEMs.
Out of the total proceeds of Rs. 10,000 mn, Rs. 1,900 mn would go towards repayment/prepayment/redemption in full or in part, of certain outstanding borrowings availed, Rs. 2,000 mn would go towards funding capex for capacity expansion at facility, and remaining Rs. 2,100 mn would go towards funding inorganic growth and general corporate purposes. Additionally, Rs 4,000 mn would go towards promoter selling shareholder of the company.
Key Highlights
- Global e-bike volumes are projected to rise from 8.24 mn units in CY24 to 12.5-14.5 mn units by CY31, at a CAGR of 6.0-9.0 pct. Alongside, the G&T market is expected to expand from Rs. 3.4-3.5 trillion in CY25 to Rs. 4.85-4.95 trillion by CY31, at a CAGR of 6.0-8.0 pct, while the BPT TAM is forecasted to grow from Rs. 310-352 bn in CY25 to Rs. 880-922 bn by CY31, at a CAGR of 16-18 pct, and the A&M TAM across 2W, bicycle and e-bike applications is projected to rise from Rs. 860-900 bn to Rs. 1,130-1,170 bn over same period, at a CAGR of 4.0-5.0 pct.
- HML has a first-mover position in the global e-bike powertrain market and is the only manufacturer in India producing and exporting CVT hubs and integrated electric powertrain products to e-bikes. This has helped them establishing strong relationship withglobal players like BMW, Ducati, enviolo, Formula Motorsport, Hummingbird EV and HWA, along with leading global e-bike manufacturers.
- HML’s diversified product portfolio, backed by in-house design, engineering, manufacturing and validation capabilities, enables it to cater both EVs and ICEs. Products in its G&T and A&M segments are powertrain neutral, catering to EVs, ICEs, and hybrid vehicles. While BPT segment caters exclusively to the EV market.
- HML operates six manufacturing facilities across India, UK and Thailand, strategically located to ensure proximity to customers and cost competitiveness. Additionally, they operate two technology centres in the UK and India – positioning it among the few in India to operate an international product development and design centre.
- HML is focused on increasing the collective contribution from systems and e-mobility related products and services, through securing additional orders. To capture these incoming demand, HML intends to expand capacity at one of its plant through the purchase of required equipment and to further expand its footprint, they intent to set up two additional facilities.
- HML is strengthening partnerships with global players to access advanced technologies, develop new products and expand its capabilities and market reach. Key collaborations include (i) partnership with Enviolo for co-developing economical CVT hubs for Indian, ASEAN and global e-bike markets, (ii) HYM – JV with Yamaha Motors for hub motor-based electric drive units, leveraging Yamaha’s motor technology and HML’s manufacturing capabilities, (iii) partnership with German automotive technology company for DCT transmissions through technology licensing and related engineering and marketing services, and (iv) Munjal STP Industries, a JV with Germany-based STP Group for manufacturing high-precision forging components for global automotive markets.
- HML’s key growth strategies include (i) To focus on providing complete systems and powertrain solutions for E-Mobility segment, (ii) expand into other market segments and geographies, (iii) leverage Hewland’s expertise for design-to-cost product and service solutions, (v) focus on strengthening partnerships with global players for technology, and (vi) pursue inorganic growth opportunities.
- The sales of the company have grown by 5.66 pct CAGR over FY24-26 and EBITDA/profit has grown 30.87 pct CAGR/55.68 pct CAGR over same year. In FY26 the company reported sales of Rs. 11,884 rose by 9.07 pct YoY. EBITDA of the company rose by 29.65 pct YoY to Rs. 1,478 mn. In FY26 the company posted profit of Rs. 412 mn, which increased by 25.61 pct YoY.
Key Risk
- HML’s operation are dependent on the performance of e-bikes and two wheelers industries, any adverse changes in the conditions affecting these industries can adversely impact its business and results of operations.
- HML’s subsidiaries have suffered losses in the last three Fiscals, with no assurance of profitability further, these continued losses could affect the results.
- HMLs operations are subject to strict customer quality and delivery requirement, exposing the company to recalls, warranty claims or order cancellations that could materially affect results.
Financial Performance
| Particulars (Rs. mn) | FY24 | FY25 | FY26 | CAGR | YoY |
| Sales | 10,644 | 10,896 | 11,884 | 5.66% | 9.07% |
| EBITDA | 863 | 1,140 | 1,478 | 30.87% | 29.65% |
| EBITDA Margin % | 8.11% | 10.46% | 12.44% | ||
| Profit | 170 | 328 | 412 | 55.68% | 25.61% |
| Profit Margin % | 1.60% | 3.01% | 3.47% | ||
| ROE % | 4.54% | 7.70% | 8.56% | ||
| ROCE % | 23.23% | 18.84% | 19.77% | ||
| Net Debt to EBITDA (X) | 1.72 | 2.79 | 2.24 | ||
| Fixed Asset Turnover (X) | 2.40 | 1.89 | 1.83 |
Source: – RHP.
Peer Comparison based on FY26 Financials.
| Particulars (Rs. mn) | Hero Motors | UNO Minda | Endurance Technologies | Varroc Engineering | CIE Automotive |
| Sales | 11,884 | 1,96,576 | 1,45,959 | 88,905 | 94,065 |
| EBITDA | 1,478 | 25,070 | 20,687 | 8,074 | 14,660 |
| EBITDA Margin % | 12.44% | 12.75% | 14.17% | 9.08% | 15.59% |
| Profit | 412 | 12,841 | 9,517 | 2,298 | 8,230 |
| Profit Margin % | 3.47% | 6.53% | 6.52% | 2.58% | 8.75% |
| ROE % | 8.56% | 17.69% | 13.91% | 12.64% | 11.03% |
| ROCE % | 19.77% | 28.83% | 38.63% | 36.53% | 24.50% |
| Net Debt to EBITDA (X) | 2.24 | 0.86 | 0.09 | 0.65 | 0.09 |
| Fixed Asset Turnover (X) | 1.83 | 3.63 | 2.67 | 4.31 | 2.95 |
Source: – RHP.
Valuation
Hero Motors Limited is the automotive flagship company of the Hero Group. HML supply a wide range of best-in-class products and end-to-end solutions in Gears & Transmission, Alloy & Metallic parts and Bike Powertrain systems to premium brands in the Motorcycle, Automotive, Off Road and Electric Vehicle (EV) segments. At the upper end of the price band of Rs. 84, the issue is priced at an PE of 92.31x its FY26 post issue capital. The issue appears to be fully priced.
Disclaimer: The views shared in blogs are based on personal opinions and do not reflect the company’s views. Investment involves risk, and it is advisable to consult a financial advisor before making any investment through the app. The decision to invest is solely that of the investor, and the company or its communication cannot be held responsible for it.